GLEG UK Energy Market Update 31-08-26…
August 31, 2026
Zero Waste Week: Making Better Use of Business Resources
September 9, 2026
UK Energy Market Summary to Friday 4th September 2026
Closing prices 04.09.2026
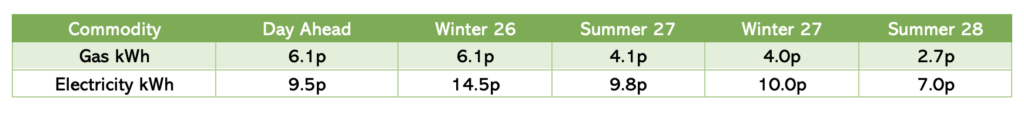
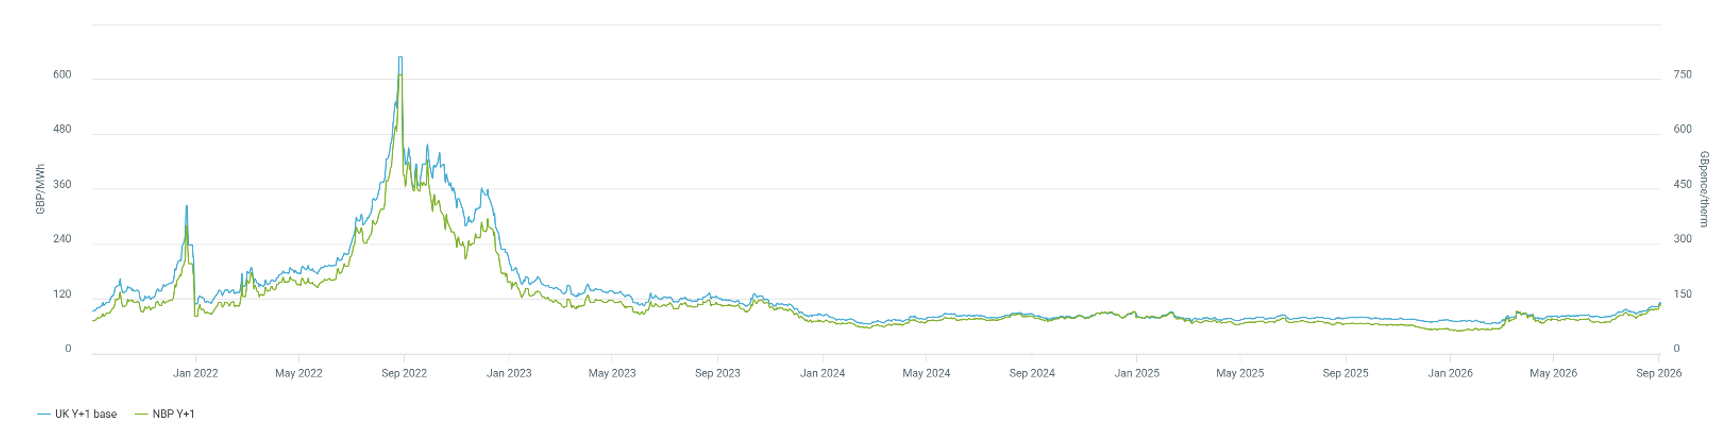
Wholesale gas, power and oil markets all strengthened during the week ending 4th September. UK NBP Winter-26 gas increased by approximately 4.8% to around 178p/therm, while day-ahead gas reached approximately 175p/therm. Renewed Middle East hostilities, disruption to Gulf LNG flows, Norwegian maintenance and low European storage kept winter supply risk firmly priced into the market. UK Winter-26 electricity rose by approximately 5.4% to £145.0/MWh as higher gas costs fed through into power prices. Brent crude increased by 7.8% to $96.28/bbl.
European gas storage continued to rebuild, reaching approximately 66.3% by 4th September. However, this remains materially below the typical seasonal level of around 80%, with particularly low stocks in Germany and the Netherlands. Europe therefore remains dependent on reliable Norwegian pipeline flows, sufficient LNG availability and sustained injections ahead of winter. The forward curve remains strongly backwardated: calendar-28 gas averaged approximately 82p/therm and electricity £74/MWh, materially below Winter-26.
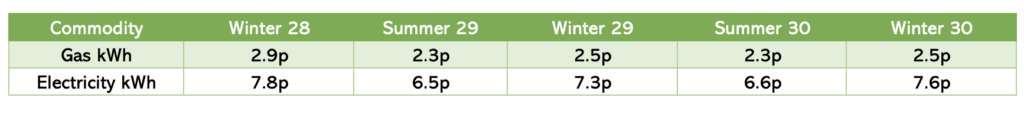
Although near-term prices have risen sharply, the forward curve continues to offer more attractive value from 2028 onwards, with electricity trading at approximately 6.5p to 7.8p/kWh and gas at 2.3p to 2.9p/kWh. Businesses should consider securing a measured proportion of future requirements where these levels support budgets, improving long-term cost certainty and reducing exposure to further geopolitical or supply-driven volatility while retaining flexibility should market conditions improve.
Curve UK Gas & Electricity Markets
Other Energy Markets
Brent crude rose by approximately 7.8% during the week to $96.28/bbl, reversing the previous week’s decline and recording its strongest weekly increase since July. Prices strengthened following renewed military action between the US and Iran, attacks on commercial shipping and threats to energy infrastructure across the Gulf. Continued shipments through the Strait of Hormuz and higher Iraqi exports provided some reassurance, but concerns over further disruption kept a substantial geopolitical premium priced into the market.