UK Sustainability Reporting Standards: What do businesses need to know?
November 4, 2026
10 Smart Ways Hospitality Operators Can Cut Energy Costs
November 11, 2026
UK Energy Market Summary to Friday 6th November 2026
Closing prices 06.11.2026
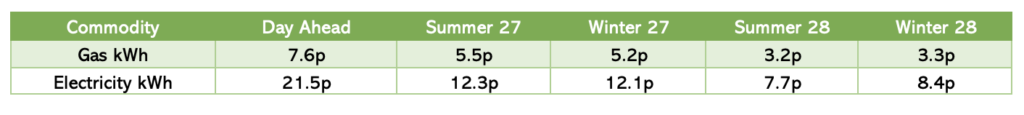
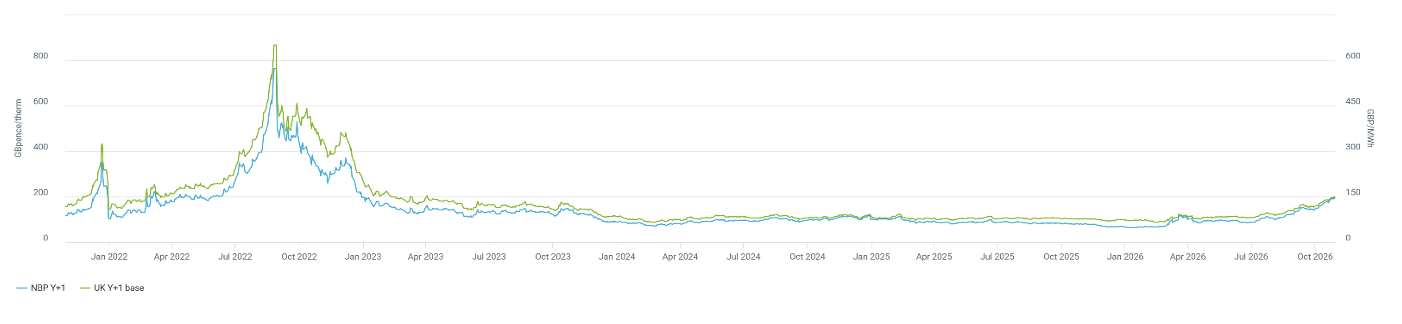
Wholesale energy markets fell overall during the week ending Friday 6th November, reversing part of the previous week’s sharp increases. Hopes of progress in US-Iran negotiations helped ease the geopolitical risk premium, although prices remained volatile. UK day-ahead gas fell approximately 7.4% week-on-week, while December-26 gas declined around 17.6%. Electricity forward prices also softened, with Summer-27 falling to approximately 12.31p/kWh and Winter-27 to 12.10p/kWh, down around 10.5% and 11.5% respectively.
European gas storage remained a concern despite the price correction. The latest reported figures during the week showed EU storage approximately 73.8% full as at 4th November, around 17.5 percentage points below the five-year seasonal average of 91.3%. Norway’s Visund field outage was extended until at least 16th November, while forecasts for colder weather and lower wind generation increased the potential call on gas. These pressures contributed to a rebound on Thursday, highlighting Europe’s continued sensitivity to weather, supply outages and developments in the Middle East.
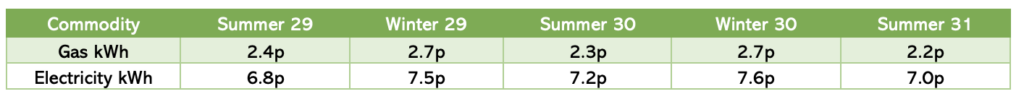
Forward markets continued to offer considerably lower prices for later delivery periods. Summer-27 gas ended the week at approximately 5.39p/kWh, with Winter-27 at 5.15p/kWh, compared with Summer-28 at around 3.16p/kWh. Electricity for Summer-27 stood at approximately 12.31p/kWh, while Summer-28 was around 7.65p/kWh. Although prices fell across the forward curve, the substantial premium for nearer delivery periods continued to reflect concerns over winter supply and subsequent storage replenishment. The correction improved buying opportunities, but the market remained exposed to renewed disruption.
Curve UK Gas & Electricity Markets
Other Energy Markets
Other News
Brent crude settled at approximately $98.32/bbl on Friday 6th November following a sharp decline during the week. Hopes of progress towards a US-Iran agreement and improving Gulf exports reduced some of the geopolitical risk premium. However, continued threats to shipping through the Strait of Hormuz kept supply concerns elevated, contributing to a rebound on Thursday. Oil markets remained sensitive to diplomatic developments and the security of regional export routes.
GLEG recommends the week’s fall in wholesale prices provides an opportunity for businesses with unhedged Winter-26 and Q1-27 requirements to review phased purchasing within agreed risk limits. For 2027–2030 requirements, measured layering can help secure longer-term prices while retaining flexibility. With European storage below seasonal norms and geopolitical uncertainty continuing, a structured procurement strategy remains preferable to relying on further price falls.