Could Your Business Reduce Its Electricity Costs Through the EII Scheme?
September 23, 2026
BICS Applications Are Now Open
October 7, 2026
UK Energy Market Summary to Friday 2nd October 2026
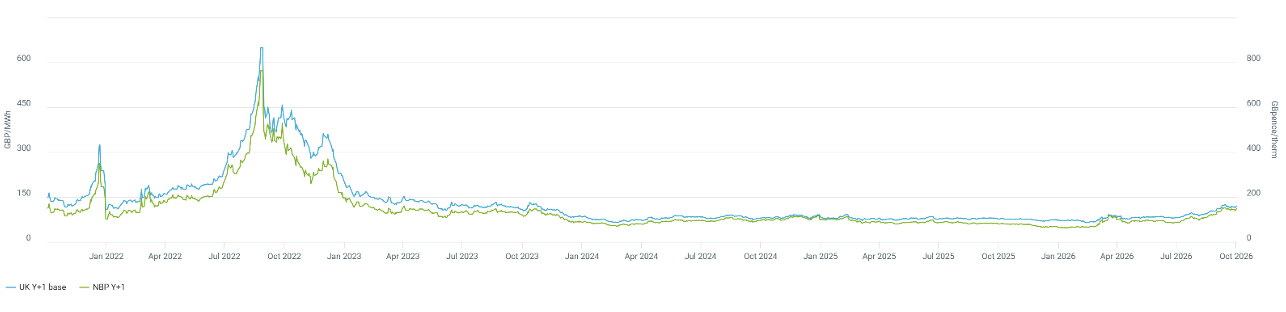
Closing prices 02.10.2026
Wholesale gas, power and oil markets remained volatile during the week ending 2nd October, with the forward curve generally moving higher despite some easing in prompt markets. UK NBP day-ahead gas settled at approximately 181.5p/therm, while Winter-26 gas closed around 188.1p/therm. UK Winter-26 electricity remained elevated at approximately £153/MWh, while Brent crude settled at $102.25/bbl. Renewed tanker attacks in the Strait of Hormuz, ongoing Middle Eastern supply uncertainty and low European storage continued to support a significant risk premium.
European gas storage increased to approximately 72%, but remained around 19 percentage points below the five-year seasonal average. Norway’s maintenance programme has largely cleared, with Gassco confirming the country’s system is ready to meet elevated winter demand. However, Europe’s storage deficit and continued reliance on competitive LNG imports leave the market exposed to further supply disruption or colder-than-expected winter demand.
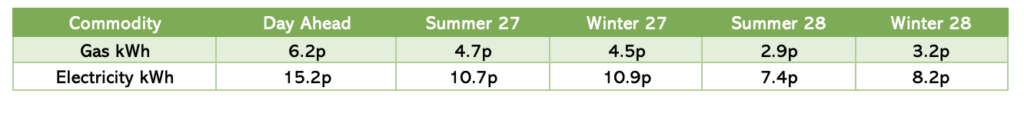
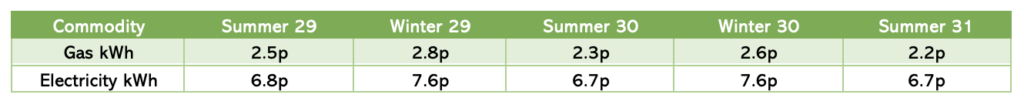
The forward curve remains materially backwardated, although prices across the curve strengthened during the week. Summer-27 gas closed around 4.68p/kWh and Summer-27 electricity around 10.7p/kwh, while Winter-28 gas was approximately 3.19p/kWh and Winter-28 electricity around 8.2p/kwh. Contracts from 2028 onwards continue to offer significantly better absolute value than near-term winter periods, although the recent upward movement reinforces the case for measured forward purchasing rather than relying on further price falls.
Businesses should consider securing a measured proportion of future requirements where current prices remain within budget, particularly where exposure extends into 2027–2030. A phased approach allows businesses to capture current backwardation while retaining flexibility to benefit from any improvement in storage, Norwegian supply or geopolitics.
Curve UK Gas & Electricity Markets
Other Energy Markets
Other News
Brent crude remained volatile during the week, settling at approximately $102.25/bbl on Friday, as recovering Middle Eastern exports and the G7’s decision to release 100 million barrels of crude and diesel eased some immediate supply concerns. However, continued attacks on vessels in the Strait of Hormuz, elevated tanker insurance costs and damage to regional capacity continue to support a significant geopolitical and logistical premium. G7’s release should provide near-term relief, particularly to tight diesel markets, but doesn’t address the underlying transport and infrastructure constraints.